ServicesFinancial Planning
Financial Planning in Freehold, NJ
We build a written financial plan that connects your income, savings, debt, insurance and retirement goals into one clear picture. The planner who learns your situation in the first meeting is the one who writes the plan and sits down with you to update it as life changes.
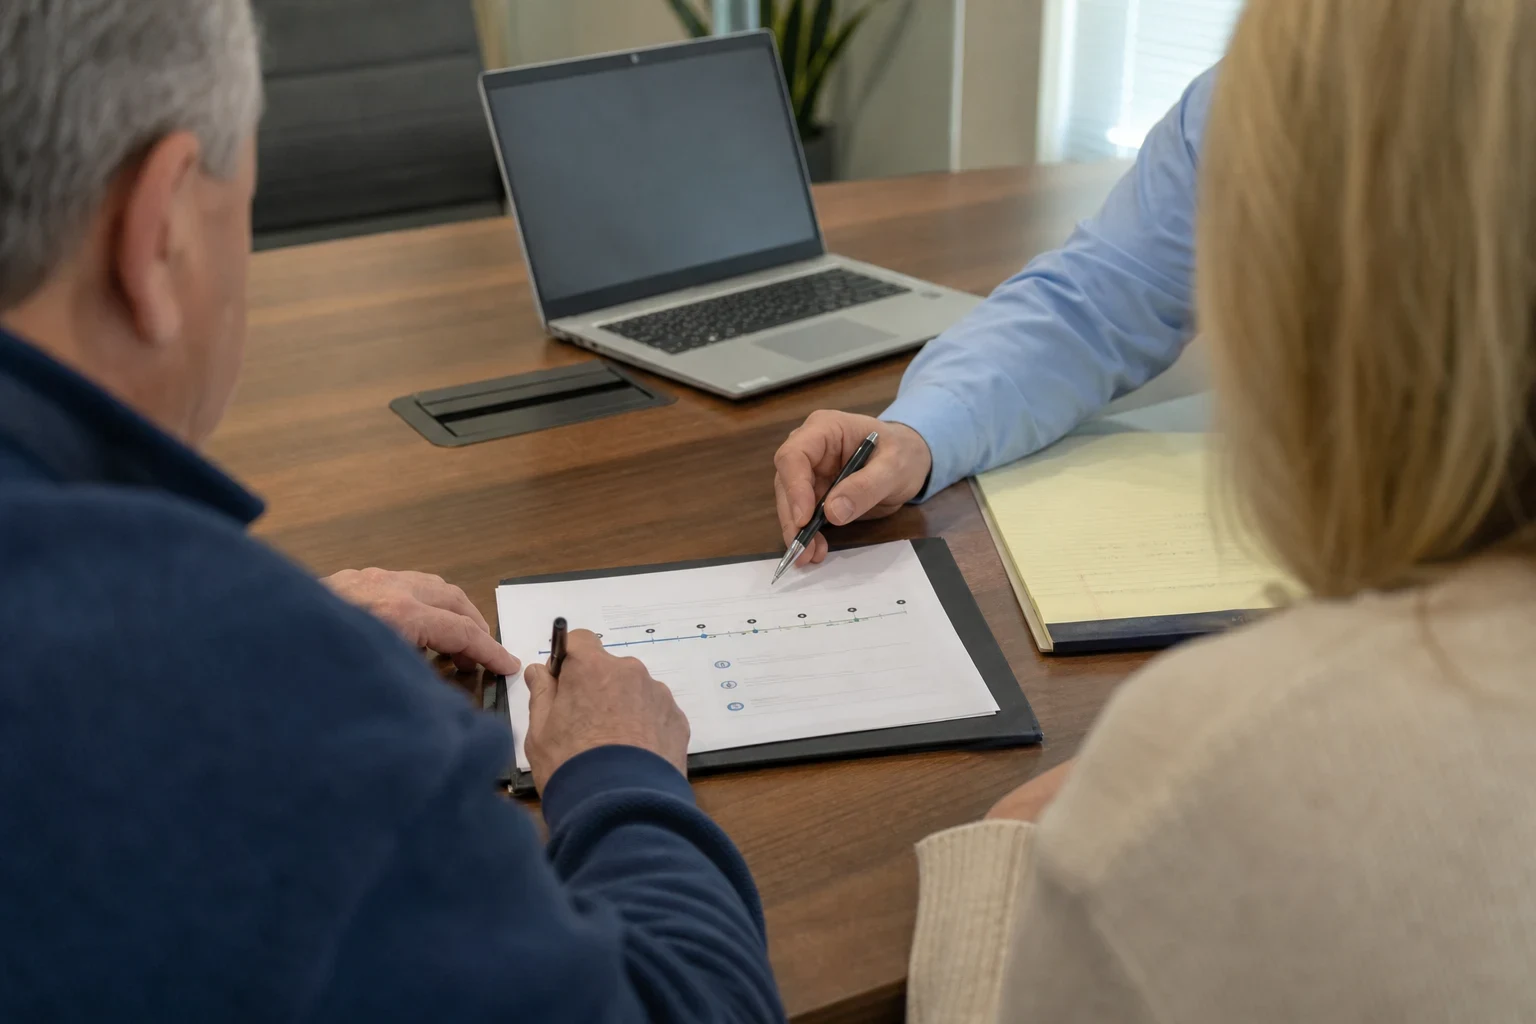
A plan that shows how the pieces fit
Most people we meet already have parts of a plan. There is a 401(k) at work, an IRA from a past job, a life policy bought years ago and a savings account meant for something nobody wrote down. Financial planning puts all of it on one page and asks a simple question: does this actually support what you want, whether that is retiring at a certain age, paying for college, starting a business or helping a parent?
We are a small team, and we work that way on purpose. The person who gathers your documents builds the projections, presents the plan and takes your call a year later. You will not be passed to a new associate each time or asked to retell your story.
We are Series 66 licensed and hold the Chartered Retirement Planning Counselor (CRPC) designation, so the retirement side of your plan gets the same careful attention as the years leading up to it.
What your financial plan covers
- Cash flow review
- We look at what comes in, what goes out and what is left each month. From there we set a savings rate you can keep, not one that only works on paper.
- Goal-by-goal projections
- Each goal gets its own projection with the assumptions written down: inflation, expected returns, timing. We also show what happens if returns come in lower than hoped, so the plan holds up in an ordinary bad year.
- Order of operations
- Pay down the car loan or fund the Roth first? Capture the full employer match? We set a clear sequence for debt, cash reserves and long-term saving.
- Protection check
- We review life, disability and liability coverage for gaps or overlap. When a policy needs a closer look, our Life Insurance Consulting work picks up from there.
- Tax and estate touchpoints
- We flag beneficiary designations that no longer match your wishes, Roth versus traditional choices, and where New Jersey inheritance tax could affect certain heirs. We coordinate with your CPA and attorney rather than replacing them.
- A written action list
- You leave with a plain document and a short list of next steps, each with an owner and a date.
Signs it is time for a financial plan
Accounts are scattered
Old 401(k)s, a brokerage account, a pension statement in a drawer. If you cannot say what you own in one sentence, a plan is overdue.
A big decision is coming
A job change, selling a business, an inheritance or a child heading to college. These choices are easier to make once you can see the full picture.
You save but cannot tell if it is enough
Saving steadily without a target leaves you guessing. A plan turns the guess into a number you can measure against.
You and your spouse have different answers
When two people picture retirement differently, the plan becomes the place to talk it through with real figures.
Retirement is ten or fifteen years away
This is the window where contribution choices, Social Security timing and investment mix start to matter most.
What shapes the cost of a financial plan
The cost of planning depends on how much there is to plan for. We explain how we are paid and what your plan will involve during the introductory meeting, before any work begins. That way the cost is settled before you commit to anything.
Complexity of your finances
A salaried couple with two retirement accounts needs less modeling than someone with rental property, stock options and several old pensions.
Business ownership
Owners bring extra layers: business retirement plans, succession questions and income that changes year to year.
One-time plan or ongoing relationship
A single written plan is a different scope from yearly reviews and ongoing adjustments. We will tell you which we think fits.
Family and coordination needs
Blended families, aging parents and work alongside your CPA or attorney all add time to the plan.
How we build your plan
- 1
Introductory meeting
We talk about your goals, your concerns and what prompted the call. We explain how we work and how we are paid, and you decide whether to go further.
- 2
Gathering the details
We ask for statements, pay stubs, tax returns, insurance policies and any estate documents. Meetings happen at our office or by phone and video, whichever suits you.
- 3
Presenting the plan
We walk through the projections line by line, explain each recommendation and answer questions until it makes sense. Nothing is acted on until you agree.
- 4
Reviewing over time
We suggest at least one review a year, and another whenever life shifts. The same planner handles each review, so the conversation picks up where it left off.
Financial planning questions
How is financial planning different from investment management?
Planning looks at your whole financial life: cash flow, goals, insurance, taxes and estate. Investment management is the ongoing work of running a portfolio. Many clients use both, and the plan usually guides how the portfolio is built.
What should I bring to the first meeting?
For the introductory meeting, just your questions and a rough idea of your goals. If we move forward, we will send a short list of the documents we need, such as recent statements, tax returns and insurance policies.
Do I need a certain amount of money for a plan to be worth it?
A plan is often most useful before wealth builds up, because early choices compound. We will tell you honestly in the first conversation whether a full plan makes sense for you right now or whether a narrower review would serve you better.
Can we meet without coming into the office?
Yes. Many clients in Marlboro, Manalapan and Howell meet with us by phone or video for some or all of the process. The work and the planner are the same either way.
Will I have to move my accounts to work with you?
The plan stands on its own. If it points to changes in how your money is invested, we explain the options and you decide what to do and who handles it.
Start with a conversation about your goals
Tell us what you are planning for and what is keeping you up at night. We will explain how we would approach your plan and who you would be working with from the first meeting on.